Market View
J200 104,487.00 -0.47% J203 112,388.00 -0.45% J210 113,793.00 +0.01% J211 127,305.00 -0.26% J212 26,488.00 -1.21% J213 143,043.00 -0.73%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
RES RESILIENT 2024-06-19 4842 7675 +58.51% +24.35%
NTC NETCARE 2025-11-14 1520 1877 +23.49% +23.55%
DSY DISCOVERY 2024-08-01 14280 27844 +94.99% +41.57%
SSK STEFSTOCK 2024-06-22 146 685 +369.18% +154.18%
EQU EQUITES 2025-05-01 1515 1765 +16.50% +10.74%
Opinions (Top 5)
Code Name Date Action
ISA ISA 2026-11-16 View

16-11-2026 ISA Holdings (ISA) is a small Alt-X listed IT company offering network, internet, and information security in sub-Saharan Africa. The company claims to employ some of the leading IT security specialists and to have the tools and experience to offer effective information security solutions.

In its results for the six months to 31st August 2026 the company reported turnover up 35% and headline earnings per share (HEPS) up 24%. The company said, "...our profits before tax increased by 195% to R54.9 million, compared to R18.6 million in the prior reporting period, while our profits attributable to equity shareholders for the period increased by 139% to R35 million, compared to R14.6 million in the prior reporting period".

This looks like a good quality IT company that is profitable but has gone through a tough time. The problem is that the share is thinly traded with only about R24 000 worth of shares changing hands on average each day. This makes it risky for private investors to buy a meaningful number of shares, however, on a P:E of 11,58 and a dividend yield of 6,91% the shares looks appealing.

It was added to the Winning Shares List (WSL) on 8th February 2024 at 140c per share. It has subsequently moved up to 212c (13-11-26).

CFR RICHEMONT 2026-11-16 View

Richemont (CFR) is the world's second-largest supplier of luxury goods controlled by the Rupert family in Stellenbosch. Its sales are entirely located overseas so it is an excellent rand-hedge. Its luxury brands include Mont Blanc, Cartier, Lancel, Jaeger-LeCoultre, Van Cleef and Piaget.

It has boosted online sales to 21% of turnover by acquiring Yoox-Net-A-Porter (YNAP), Watchfinder, a UK online group and entering into a joint venture with the online giant Alibaba, to develop apps to penetrate the Chinese market and offer its line of luxury goods. At the same time, its luxury goods are offered through Alibaba's Tmall Luxury Pavilion.

Richemont is a company which is directly linked to the recovery of the world economy following the pandemic. While the company sales clearly took a hit from COVID-19, we expect them to continue rising, especially now that it is aggressively offering its products online. This share is also impacted by the slowdown in the Chinese economy and the developments in Central and Eastern Europe.

It will benefit from the recovery in the world economy but will be impacted by changes in the strength of the rand. In its results for the six months to 30th September 2026 the company reported group sales up 17% and headline earnings per share (HEPS) of 430 euro cents compared with 301c in the previous period.

The company said, "Double-digit growth across most regions throughout H1, led by Japan, the Americas and Asia Pacific. Broad-based strength across business areas in H1, including in Q2 against elevated comparatives". Richemont is clearly a rand hedge, but it is also dependent on the Chinese consumer.

Technically, it is in a strong upward trend and was added to the Winning Shares List (WSL) on 9th January 2025 at 292438c. It has since reached 396600c (15-7-26), a new all-time record high, before falling back on profit-taking. 

RLO REUNERT 2026-11-16 View

16-11-2026   Reunert (RLO) is a company involved in electrical appliances, electrical engineering, and information communications. The company has been in existence for 130 years and listed for 70 years. It has operations in Australia and Sweden as well as in Zimbabwe, Zambia, and Lesotho.

It exports to many countries around the world. Electrical engineering accounts for roughly half of its annual turnover which is about R10bn. In its results for the six months to 31st March 2026 the company reported revenue up 1% and headline earnings per share (HEPS) down 22%. The company said, "The marginal increase in revenue was driven by strong circuit breaker export volumes in the Electrical Engineering Segment and the disciplined execution on a healthy order book, which contributed to the excellent Defence Cluster performance during the period.

Revenue from the ICT Segment was lower than the prior comparative period". In a trading statement for the year to 30th September 2026 the company estimated that HEPS would fall by between 45% and 50%. The share trades on a P:E of 8,5 which looks reasonably priced to us.

However, its future performance will depend on the rand/US dollar exchange rate, a recovery in the South African economy and increased business from government and quasi-government organisations. Technically, the share has been falling since November 2024 and we advise waiting for it to break up through its downward trendline before investigating further.  We expect that in time it will recover.  

MTA METAIR 2026-11-16 View

16-11-2026   Metair (MTA) produces energy solutions (batteries) and components for the vehicle manufacturing business. It has operations in Africa and in various European and Middle East countries. The company's energy storage business is located in Turkey in an operation called "Mutlu".

The business it is in has the prospect of growing rapidly as electric motor vehicles replace those powered by internal combustion engines. The company has announced its intention to split into its European acid battery business and its automotive components business in South Africa.

In a report on the impact of the floods in Natal the company said, "Whilst the impact on Metair’s facilities was minimal and operations had promptly returned to normal, a major Original Equipment Manufacturer (OEM) customer of the Group advised that it suffered significant damage to its plant with production suspended for clean-up operations and assessments to be carried out." The company received a R150m insurance pay out for business interruption from the Natal floods.

In its results for the six months to 30th June 2026 the company reported revenue up 1% and headline earnings per share (HEPS) up 4%. The company said, "The accounting for Hesto Harnesses Proprietary Limited ("Hesto") as a subsidiary resulted in the recognition of a significant once-off net capital loss of R306 million in the first half of the 2025 financial year (H1 2025)".

In an update for the year to 31st December 2025 the company estimated that due to disruptions and problems at the Durban port thier costs would rise by between 25% and 35% of EBITDA. This had a negative impact on the share price. The share has been falling since February 2014. We recommend waiting for a break up through its downward trendline before investigating further.

The share has not yet broken up through that long-term downward trendline and has, in fact, drifted lower. 

GRSP GOLDRUSH 2026-11-13 View

13-11-2026   Previously, RECM Calibre, Goldrush is a company engaged in Bingo, Limited Payout Machines, and Retail Sports Betting. In its results for the six months to 30th September 2025 the company reported gaming revenue up 4% and headline earnings per share (HEPS) of 7,13c compared with 113,8c in the previous period.

The company said, "Food and beverage revenue, which is only associated with Bingo premises, increased by 10% to R37.5m from R34.2m. Total Income for the six months reached the R1bn level for the first time and was up 5% on the corresponding reporting period." Goldrush owns 50% of Sizekhaya which has just been awarded the lucrative R90bn contract to run the national lottery.

Business Day reported on 24th June 2025  that the awarding of this contract may be controversial as members of the National Lottery Commission (NLC) have links to the adjudication committee which decided the winner indicating a conflict of intereSt. In a trading statement for the six months to 30th September 2026 the company estimated that HEPS would be between 35c and 36,4c compared with 7,13c in the previous period.

The company said, "The difference between the LPS and the HEPS numbers reflects an impairment of Goodwill and Intangible Assets". Since the listing of Goldrush, the volume traded has dropped off substantially to an average of R28 000 per day on average. The share price has also fallen back to 620c (12-11-26) which indicates that there is considerable selling.

It is early days, but we believe that this share may be dangerous for private investors.

Winning Share: NTC
Opinion: CFR
Nvidia  (2026-11-16)

Charismatic leadership in business can often be a major problem. When a company is dominated by a single individual who then becomes incapacitated for some reason, the result is normally a sharp downward re-rating of the share. Charismatic leadership can increases the key-person risk for an…

Charismatic leadership in business can often be a major problem. When a company is dominated by a single individual who then becomes incapacitated for some reason, the result is normally a sharp downward re-rating of the share. Charismatic leadership can increases the key-person risk for an investor.

In the current case of Nvidia, the CEO, Jensen Huang, has now resigned following a series of scandals regarding his extra-marital affairs and their possible link to Chinese spying. The impact on the share price over the past month has been substantial. On 6th October 2026 Nvidia shares closed at $241,90 and on Friday last week they closed at $162,83 – that is a drop of almost one third and wiped $1,85 trillion off its market capitalisation. Consider the chart:
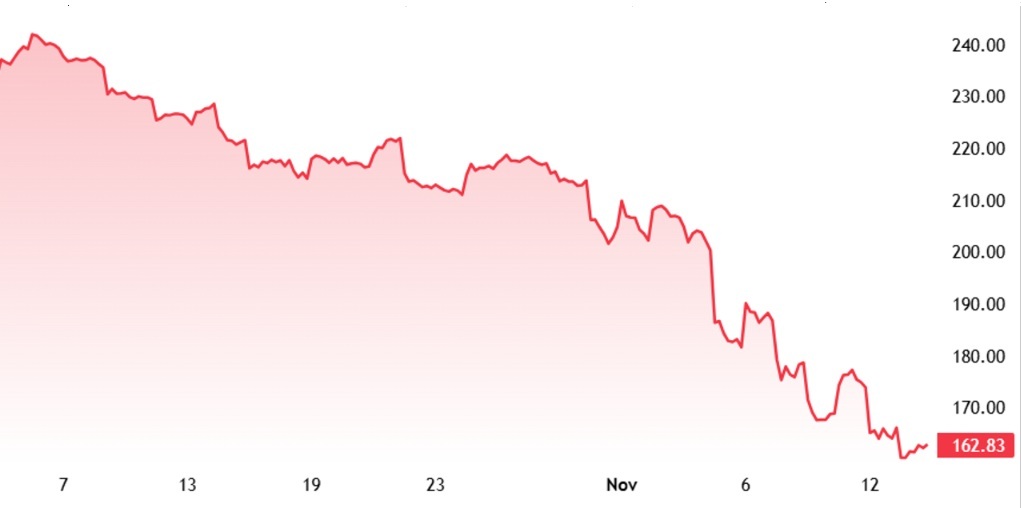
Nvidia : 7th of November 2026 - 13th of November 2026. Source: https://www.tradingview.com/symbols/NASDAQ-NVDA/?timeframe=3M


Huang was the co-founder of Nvidia in 1993 and had served as its President for 33 years. After early struggles, the company broke through with chips like the RIVA 128 and went public in 1999, the same year it introduced the GeForce 256—the world's first graphics processing unit (GPU). This led to the bold bet to launch CUDA, a parallel computing platform that allowed GPUs to handle general-purpose computing—laying the foundational software architecture for modern deep learning and artificial intelligence (AI). This scaled Nvidia into the backbone of the global AI and data centre revolution, driving the company to a multi-trillion-dollar valuation and transforming it into one of the most influential technology companies in history.

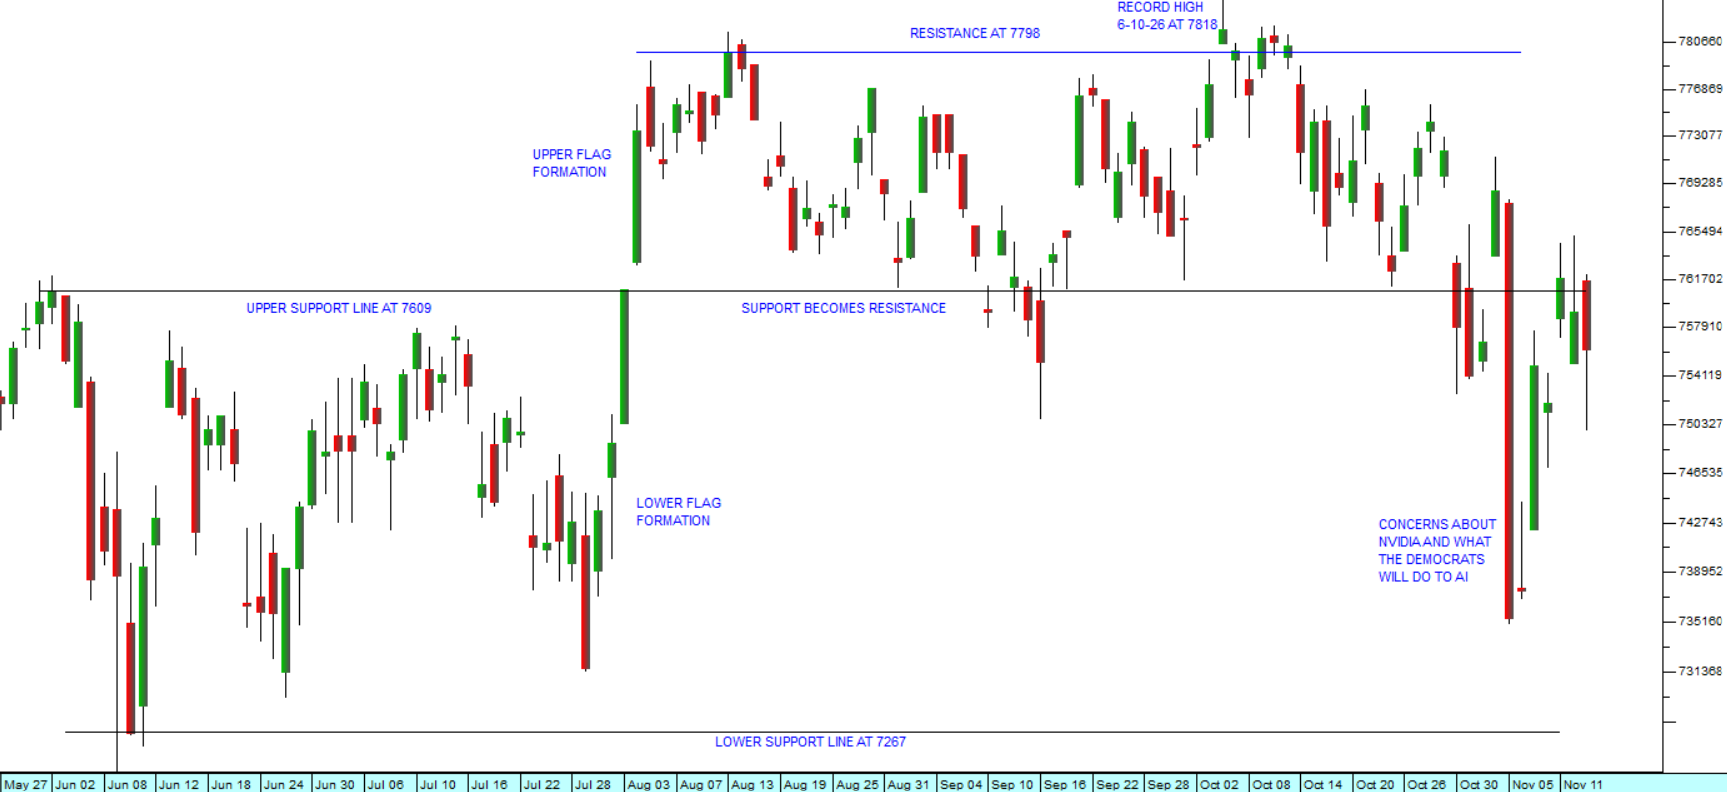
Clearly, Huang was an important person and his leadership on the Nvidia board was crucial – so when rumours began circulating of his relationship problems and the possible connection to China, investors began selling the stock as concerns about leadership uncertainty increased. What is interesting is that the sharp decline in the price of Nvidia has not dragged the other shares in the Magnificent 7 down with it, and while it was the main contributor to a correction in the S&P500, it has not precipitated a major collapse. The S&P500 also reached an all-time record high on 6th October 2026 closing at 7818, but it was only down by 3,3% from that record high at Friday’s close. Consider the chart:
S&P500 Index :  27th of May 2026 - 13th Of November 2026. Chart by ShareFriend Pro.

The chart shows that developments at Nvidia combined with concerns around what the Democrats might do to curtail the growth of AI took the S&P500 down but did not penetrate the lower support line at 7267. In our view, AI has its own momentum and is now stimulating growth in most companies across America and the world. The Democrat victory in the mid-term elections is unlikely to derail that. One major positive impact of the election was that it immediately brought the price of North Sea Brent down to $95.

In our view, the Democrat win also brings another major positive – it signals the end of the MAGA/Trump era with all the uncertainty that that entailed. Notably the JSE Overall index has actually been going up since 6th October 2026 showing that local investors never really believed that Wall Street was in a major correction. We are expecting further declines in the price of oil and fewer disruptive shocks from the Trump administration going forward.  
Democrat Sweep  (2026-11-09)

It seems fair to say that while most analysts and investors expected the Democrats to do well in the US mid-term elections, most were also caught completely off-guard by the extraordinary extent and depth of that win - and this has resulted in a burst of increased volatility in the markets as they…

It seems fair to say that while most analysts and investors expected the Democrats to do well in the US mid-term elections, most were also caught completely off-guard by the extraordinary extent and depth of that win - and this has resulted in a burst of increased volatility in the markets as they adjust to the new reality. Trump’s decision to appoint Stephen Miller as his Chief of Staff shows that he has no intention of moderating his position by working with the Democrats – instead he is doubling down on the extreme right-wing politics which has made him so unpopular.

The initial reaction to the vote was undoubtedly one of relief and euphoria as the Democrats claimed first the House and then the Senate. Then the next day that excitement gave way to fear that they might use their now overwhelming power to somehow curtail or limit AI and the build out of data centres across America.

This led, the next day, to a massive 4,4% drop in the S&P500, completely wiping out the gains of the previous day and taking the NASDAQ particularly, down sharply. Voters and newly elected officials have already passed dozens of local measures restricting data centres (from outright bans to temporary moratoriums), while incoming governors in states like Texas and Georgia have signalled plans to pause or heavily regulate new construction.

Hyperscalers and data centre operators have been funding massive expansions with heavy borrowing and private credit. Rising AI credit costs and heavy debt loads have sparked fears among investors of financial strain, stranded assets, or potential defaults if demand falls short. What if the direction of the technology changes and these huge investments are suddenly irrelevant and there is an unsupportable overhang of debt and abandoned assets?

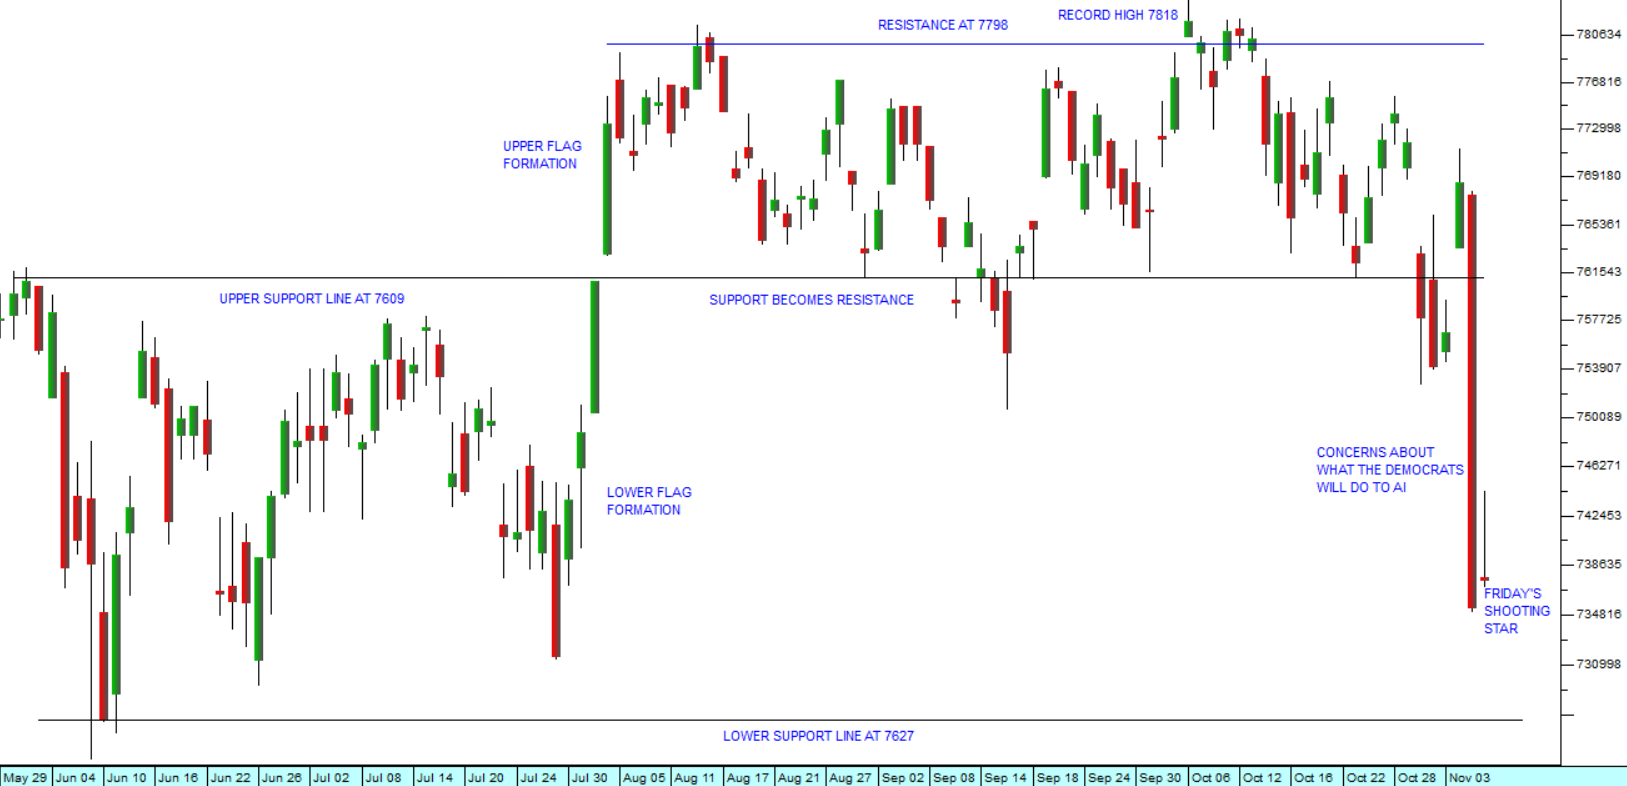
Those fears, added to the fact that tech shares were very already high and due for some kind of correction, has led to a rapid rotation out of AI and into other sectors or into cash. Consider the chart:

S&P500 Index : 29th of May 2026 - 6th of November 2026. Chart by ShareFriend Pro.

Of course, the Anthropic IPO is due to happen on 19th November 2026 and their prospectus has already been issued. They are looking to raise between $80bn and $100bn off a market valuation of between $1,5tr to $2tr. That will now almost certainly have to be curtailed – possibly to as little as $1tr. While Anthropic showed explosive growth - posting $16.3 billion in revenue for the first half of 2026 (up 1,300% year-over-year) - it also recorded an $80.7 billion net loss during that same period.

As a private investor on the JSE watching all this unfold on world markets and with our own election results in the background, you must obviously ask how these things will impact on emerging markets and on South Africa in particular. Our markets, and especially the rand have remained remarkably stable throughout the turbulence. The rand weakened, as far as R16,75 to the US$ and strengthened as far as R16,35, and now has settled in the middle ground of R16,51. This shows that the sharp downward move on Wall Street has not resulted in a huge shift towards risk-off among international investors. The smart money is still buying South African high-yield bonds and our relatively cheap high-quality equities.

On Friday, the US markets stabilised with many investors buying the dip and other even going as far as selling put options for a quick gain if the market recovers some of its former balance. However, the  shooting star formation does not bode well for the coming week. From a purely technical perspective, the lower support line on the S&P at 7626 now becomes important. If that is broken then we are in a full-blown correction.

Against this, we look at the underlying fundamentals of the third quarter S&P500 company earnings and feel that, at the very least, the Thursday sell-off was over-done. At this time 88,2% of S&P500 companies have reported and 82% of those have beaten earnings projections while 74,6% beat revenue expectations. This shows that the bull trend has been very well supported by rising profits across the board. In other words, it does not have the look of a bubble in the throes of bursting. But, in these turbulent times, your ultimate protection remains your stop-loss strategy.

Sasol and the Rising Oil Price  (2026-10-26)

Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran. At the time that the war began with the Israeli and American bombing raids on 28th…

Every major event that happens in the world inevitably offers some kind of investment opportunity for the private investor. The challenge is to work out how best to capitalise on it. So, it was with the war in Iran.

At the time that the war began with the Israeli and American bombing raids on 28th February 2026, we had already been watching the progress of Sasol for some time. The situation in Iran was tense with riots reported and North Sea Brent had climbed back up to $70 per barrel, but we had no idea that the Americans and Israelis were about to launch a bombing attack.

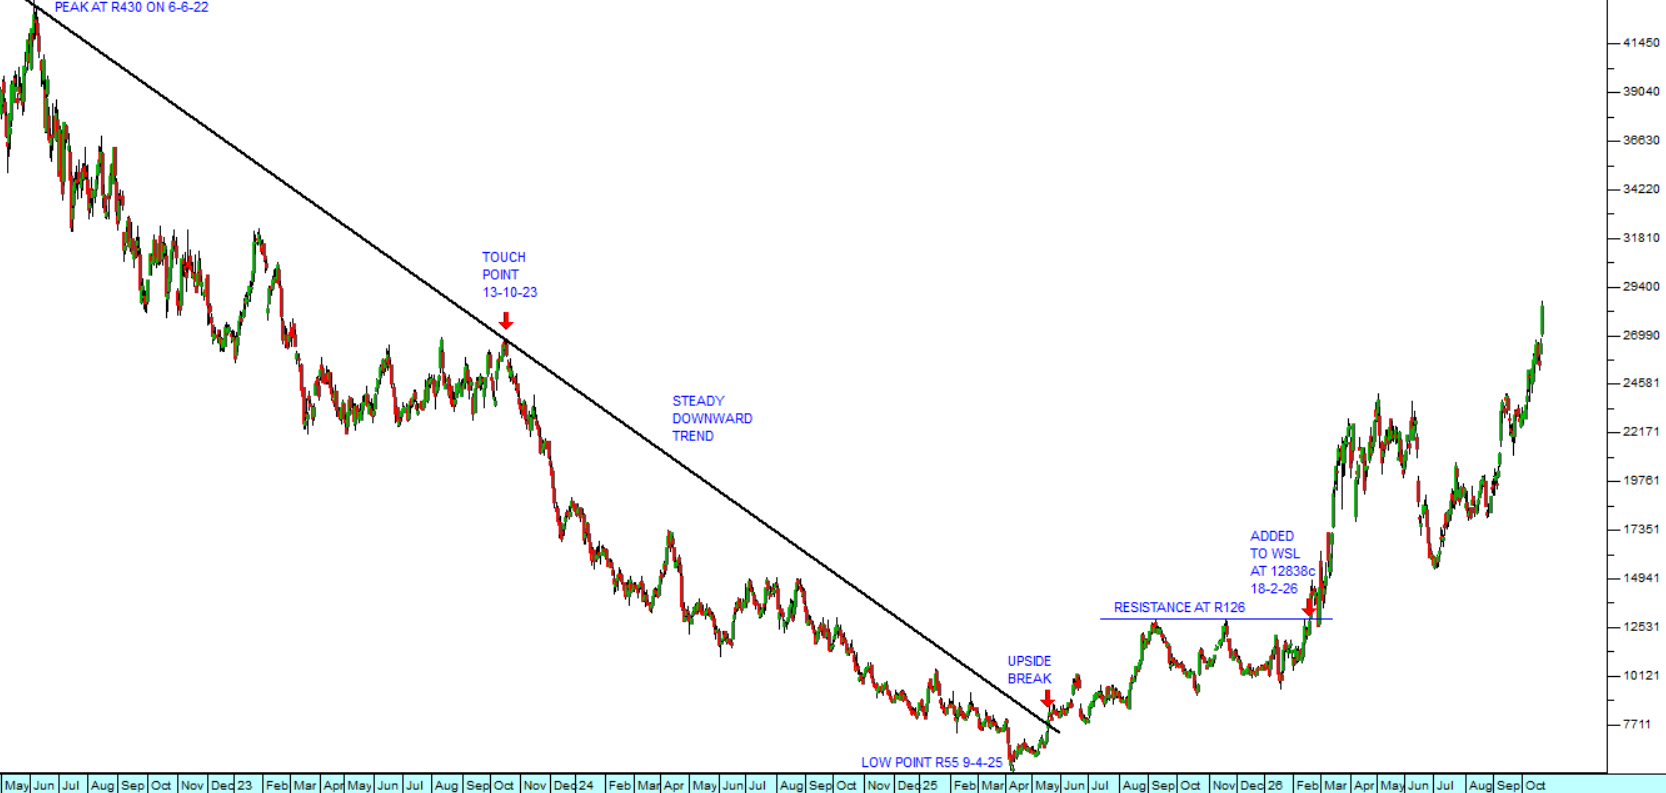
Sasol was always a blue-chip share and has historically occupied a dominant position in South Africa's synthetic fuels industry. It had, however been through some difficult times and the share price had fallen from a high of R430 per share to as low as R55 in April 2025. It then went through an extended period of sideways consolidation. We finally decided to add it to the Winning Shares List (WSL) on 18th February 2026 at a price of R128.36. Technically the share broke above resistance at R126 indicating that something was afoot. Consider the chart:

Sasol (SOL) : May 2022 - 23rd of October 2026. Chart by ShareFriend Pro.

The chart shows Sasol’s long downward trend that began in the middle of 2022, mainly because of the falling price of various grades of oil. North Sea Brent oil fell from a high of $125 per barrel on 8th March 2022 to its cycle low just below $60 per barrel in mid-December 2025. Since Sasol derives more than half of its revenues and profits from the fuel industry, it is directly linked to the price of oil.

Sasol had been recovering but had encountered significant resistance at R126 per share. When it broke decisively above that level, that gave us the signal we needed. Immediately prior to the start of the war the oil price had been climbing, and in January 2026 there were riots in Iran which Trump and Netanyahu used as a pretext to begin the bombing. The price of Brent rose above $70 per barrel on 18th February, before the bombing started, and that triggered a rise in Sasol’s share price. We decided then that Sasol was probably under-valued and due for an upside move.

Sasol’s latest results for the year to 30th June 2026 show the benefits of the rising price of oil. Turnover was up 9% and earnings before interest taxation depreciation and amortisation (EBITDA) was up 17% while the company reduced its debt by 11%.

We do not normally advise investors to buy commodity shares like Sasol because they are riskier, but sometimes they can offer very good capital gains. In the case of Sasol the share appreciated rapidly after we added it to the WSL and then there was a correction as the oil price temporarily fell back in June and July this year. We held on because we thought there might be further upside potential.

The best investment policy is to try to hold onto your shares for at least three years, unless you are moving into a loss position (i.e. you had to execute an early stop-loss sale). This is because if you hold them for less than 3 years the Receiver may seek to declare you to be a share dealer – and then any gain you make will be added to your taxable income and you will be taxed on it at your marginal rate. If you hold for longer than 3 years, then your appreciation is treated as a capital gain for tax purposes and taxed at 18%.

As it turns out holding on to Sasol was the right decision and the share has now appreciated by 134% in about 8 months since we added it to the WSL – which is just shy of 200% per annum.

JSE Top 40

104,487.00 (-0.47%)

All Share

112,388.00 (-0.45%)

Financial 15

26,488.00 (-1.21%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 MCZ MC-MINING 258 +29.00%
2 CHP CHOPPIES 88 +25.71%
3 CNP CANALPLUS 5500 +25.00%
Top Losers
# Code Name Close (c) % move
1 MTA METAIR 295 -35.59%
2 MKR MNTKRENEW 1999 -28.63%
3 ISB INSIMBI 60 -24.05%

Top Movers – Charts

Top Gainer: MCZ
Top Loser: MTA