Market View
J200 105,242.00 -1.23% J203 113,002.00 -1.01% J210 129,008.00 -2.52% J211 118,831.00 -0.31% J212 25,500.00 -0.62% J213 135,340.00 -0.47%
Winning Shares (Top 5)
Code Name Added Price Latest % Gain % Gain/Year
GND GRINDROD 2025-08-23 1446 2988 +106.64% +99.55%
HAR HARMONY 2023-11-16 9920 31971 +222.29% +78.24%
SBK STANBANK 2025-08-15 24911 30995 +24.42% +22.34%
SHP SHOPRIT 2026-05-15 29225 31856 +9.00% +26.08%
RBO RAINBOW 2025-07-24 417 634 +52.04% +45.12%
Opinions (Top 5)
Code Name Date Action
REM REMGRO 2026-09-21 View

21-09-2026   Johann Rupert's Remgro (REM) is an investment holding company which owns 28,2% of Rand Merchant Bank Holdings (RMH) and 3,9% of Firstrand. But that is not Remgro's only investment. It also owns Mediclinic, an international healthcare company with divisions in Switzerland, Southern Africa and United Arab Emirates which has now been delisted from the JSE.

Remgro recently sold its 25,8% stake in the London-listed Unilever Group for R4,9bn in cash plus the Unilever spreads business in Southern Africa. This gave it ownership of brands like Flora and Rama and other spreads. In its foods division it also owns 31,8% of Distell and 77,2% of RCL Foods (where the Unilever spreads division may be housed in a new subsidiary called "Silver 2017").

Under insurance, Remgro owns 29,9% of RMI. It owns a number of other investments including a 23,1% stake in Grindrod and a 30% stake in Seacom. The Competition Tribunal has approved the acquisition by Community Investment Ventures Holdings (CIVH), a Remgro subsidiary, of Vumatel.

Vumatel is a "last mile" fibre infrastructure company. In terms of the approval, Vumatel must supply free uncapped fibre services to schools near where it's networks pass for the next 10 years. On 2nd December 2020 Remgro announced that it is planning to increase its stake in RCL Foods at a cost of R805m.

The company has the intention of getting into the electricity generation business to supply its own businesses because it believes that Eskom can no longer be relied upon. In its results for the year to 30th June 2026 the company reported headline earnings per share (HEPS) up 42,2% and intrinsic net asset value (NAV) up 4,6%.

The company said, "...increased contribution from Mediclinic Holdings Limited (Mediclinic) (+R1 367 million), increased contributions from Rainbow Chicken Limited (+R610 million), increased contribution from TotalEnergies Marketing South Africa Proprietary Limited (TotalEnergies) (+R424 million)". While the Iran war has had a negative impact on the share price, this is a very high-quality blue chip which should be accumulated on weakness.

Technically, the share made a low at 8388c on 7th September 2020 and has been in a rising trend since. It is currently trading at 20215c (18-9-26) on a P:E of 12,2. We see further upside potential in the share.

INP INVPLC 2026-09-21 View

21/09/2026   Investec Plc (INP) is the holding company for most of Investec's non-Southern African operations. It is controlled by the same group of shareholders that own and control Investec Limited but with different percentage shareholdings. It has the same board of directors.

Investec Plc began in 1992 with the acquisition by Investec Ltd of Allied Trust Bank in the UK and then in 1998 with the acquisition of Guinness Mahon and Henderson Crosthwaie (a stockbroking company). The company has operations in South Africa, the UK, Australia and Ireland. Investec was the first company to be dual listed on the JSE and the London Stock Exchange and it is now one of the companies in the FTSE 250 index.

Investec Plc and Investec Ltd are separate companies connected by legal contracts. Although separate entities, the two companies have common goals and only their creditors are separate. They have identical price:earnings (P:E) ratios and dividend yields (DY) and their share prices are very similar.

In the combined financial results of Investec Ltd (INL) and Investec Plc (INP) for the year to 31st March 2022 the company reported revenue up 21,3% and adjusted earnings per share (EPS) up 90,7%. Funds under management increased by 9,2% and tangible net asset value (NAV) per share increased by 12,5% to 476,6p.

The CEO, Fani Titi, said, "With the pending distribution of 15% of Ninety One to shareholders, Investec would have returned an aggregate value of approximately £1.6 billion or c.R32 billion (per Ninety One closing share price on 16 May 2022) to shareholders through the demerger and distribution on successful completion". In a trading statement for the six months to 30th September 2026 the company estimated that HEPS would increase by between 4% and 8%.

The company said, "The Southern African business adjusted operating profit is expected to be up to 6% ahead of the prior period in Rands and up to 14% in Pounds Sterling (1H2026: R5 733 million, £238.0 million)". Technically the shares are in a strong upward trend which we expect to continue.

MTM MOMMET 2026-09-18 View

18-09-2026   Momentum Metropolitan (MTM) is an insurance company listed on the JSE and the Namibian stock exchanges. It was formed by the merger of Momentum and Metropolitan in December 2010. The company participates in all aspects of short and long-term insurances and various financial services.

The company was the first insurance company to achieve level 1 BBBEE status. The company is closing its businesses in Mozambique, Mauritius, Zambia, Tanzania, and Swaziland. At the time of the merger between Momentum and Metropolitan, they had a combined 24% of the life insurance market in South Africa.

Today that has been reduced to just 17%. The company paid out almost R4bn in death claims in the 1st quarter of 2021 - three times higher than it anticipated, mainly due to the 2nd wave of the virus. The company said that it would consider managing with about 60% of its current office space because of the move to work-from-home as a result of COVID19.

In its results for the year to 30 June 2026, Momentum Metropolitan reported headline earnings per share (HEPS) up 18% and operating profit up 9%. Technically, the share began to move up in May 2024 and we added to the Winning Shares List (WSL) on 24th July 2024 at 2402c. It has subsequently moved up to 3820c (17-9-26) and we expect it to go further.

On a P:E of 7,23 and a dividend yield (DY) of 4,82% it still looks reasonably priced to us. Obviously, the share price has fallen in the short term as a result of the Iran war.

SAC SA-CORP 2026-09-18 View

18-09-2026   SA Corp (SAC) owns a group of 199 industrial, retail, storage, residential and office properties in South Africa plus a 50% stake in a joint venture in Zambia with 3 properties. The bulk of this portfolio is in retail (43%) and industrial (28%). The company has problems across its portfolio, and especially in its office and industrial properties where it has been experiencing negative rental reversions.

Obviously, it is exposed to the poor economic conditions facing South Africa at the moment. Various offers have been made to buy out the company which have been rejected by the board. The new (and returning) CEO, Rory Mackey, plans to turn the company around over the next year - by getting it out of the office market and concentrating on residential and retail portfolio.

On 15th March 2023 the company announced that it had made a firm offer to acquire the entire issued share capital of Indluplace (ILU) for R3.40 per share which would result in the delisting of that company. On 18th July 2023 the Indluplace announced that the deal had been approved and so we expect ILU to be delisted in due course.

In its results for the six months to 30th June 2026 the company reported revenue of R1,506m up from R1,456m in the previous period. Headline earnings per share (HEPS) was 18,32c compared with 13,33c in the previous period. The company said, "Distributable income per share Increase of 7.0% to 15.05 cps (2025 H1: 14.07 cps) Total like-for-like net property income increased by 5.5% to R655.1 million (2025 H1: R620.9 million)". Technically, the share is in an upward trend but has been negatively impacted by the war in Iran.  This should be seen as a buying opportunity.

ORN ORIONMIN 2026-09-18 View

18-09-2026   Orion Minerals (ORN) is an Australian exploration company which is listed on the JSE (September 2017) and on the Australian Stock Exchange in Sydney. It is trying to find funding for its copper and zinc mine in Prieska. The Prieska mine was previously operated by Anglovaal, but stopped operating in 1990 after 20 years during which it extracted more than 1 million tons of zinc and 430 000 tons of copper concentrate.

The main problem with the mine is flooding. Orion hopes to exploit this resource with a mechanised approach and minimum labour. Vedanta Resources which runs the Gamsberg mine next to Orion's resource is looking at building a smelter that could service all the mines in the area and even resources from Namibia.

Once construction begins on the Prieska mine, they will need to pump out nearly 9 million cubic meters of water from the existing structure. In its results for the year to 30th June 2026 the company reported and operating loss of A$12,69m and a headline loss of 12c compared with a loss of 18c in the previous period.

In our view, this is a volatile loss-making penny stock engaged in a particularly risky venture, but it may have some speculative potential. On 3rd April 2025 the company announced that Errol Smart would step down as CEO and be replaced by Anthony Lennox with immediate effect. 

Winning Share: SHP
Opinion: ORN
Using AI  (2026-09-21)

Artificial Intelligence (AI) has been sweeping the world over the past year affecting almost every field of human endeavour. The investment world is no exception. Today the private investor, through AI, has access to a range of analysis which is totally unprecedented and lightning fast. For example…

Artificial Intelligence (AI) has been sweeping the world over the past year affecting almost every field of human endeavour. The investment world is no exception. Today the private investor, through AI, has access to a range of analysis which is totally unprecedented and lightning fast. For example, if you pose the following to Google's Gemini:

“Using a price:earnings growth ratio (PEG), with historical earnings figures over the past 10 years, compare Clicks and Dischem on the JSE for relative value at their current prices”.

A few seconds later, you will receive the following answer:

Based on a 10-year historical valuation framework using the Price/Earnings-to-Growth (PEG) metric, Clicks Group Limited (CLS) offers significantly better relative value than Dis-Chem Pharmacies Limited (DCP), with Clicks holding a PEG ratio of 1,07 compared to Dis-Chem's elevated PEG ratio of 4,92. While both healthcare retailers have faced growth pressures over the past year, Clicks’ consistent long-term earnings growth profile maps to a far more sustainable valuation at current market prices.

It then goes on to say:

To understand the core drivers behind these valuation gaps, we normalize the current trailing Price-to-Earnings (P/E) ratios against their respective multi-year historical Compound Annual Growth Rates (CAGR) in Headline Earnings Per Share (HEPS).

Clicks Group (CLS) — Steady Compounder

  • Robust Growth Track Record: Over the past decade, Clicks Group has compounded its diluted HEPS at an impressive 13,5% per annum, alongside a dividend growth rate of 14,2%.
  • Defensive Cost Efficiencies: Its massive retail presence (~1,000 stores) gives it exceptional operating leverage. At a current P/E of 14,45x, the market has compressed Clicks' historical premium rating (which typically sat closer to 30x), creating a much safer entry point where the earnings growth rate almost directly mirrors its multiple.

Dis-Chem Pharmacies (DCP) — Growth Disruption

  • Earnings Volatility: While Dis-Chem Pharmacies initially listed with immense growth premium expectations in 2016, its long-term financial delivery has slowed down. For instance, its FY2026 annual performance saw a sharp 17,3% drop in HEPS to 113,7 cents due to significant operational and macroeconomic pressures.
  • Depressed Growth Base: Compounding its HEPS from its first full year post-listing (74,7 cents in FY2017) to FY2026 yields a long-term compound growth rate of only 4,78%. A P/E multiple of 23,53x is highly mismatched against this lower single-digit structural growth pace, heavily inflating its PEG ratio.

Risk Guardrails & Framework

Peter Lynch’s traditional benchmark dictates that a PEG ratio near 1,0 indicates a stock is fairly priced relative to its growth, while any metric significantly exceeding 2,0 alerts investors to potential overvaluation relative to realized history. For long-term portfolios, Clicks presents a structurally sound baseline where you are paying a reasonable price for a stable, high-return business framework, whereas Dis-Chem requires aggressive operational margin expansions (such as its automated staffing framework 2.0 initiatives) to justify its present multiple.

This analysis shows that Clicks is cheap at current prices, while Dischem is probably over-priced. Of course, you could have come to the same conclusion if you had done the work yourself, but that would be extremely laborious and time-consuming. For many months now we have been watching Clicks closely. Its price has virtually halved since the middle of last year. And when the price of a blue chip share like Clicks halves, it is always worth investigating.

Of course, before you know to ask such a question you would need to have a basic understanding of how the PEG ratio works or even that there is such a thing as the PEG ratio. Even with the advantage of AI, you need to know enough to be able to ask the right questions – but AI can help you with that too.

We are not suggesting that you let AI make your investment decisions, but we are suggesting that when you find an investment idea it can be a very powerful tool for analysis.

And we do believe that Clicks offers significant value at current levels. Certainly, we believe that it is far better value than Dischem. That is why we asked AI the question in the first place.
Muddy Waters  (2026-09-14)

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding…

It has become difficult to keep up with all the news coming out of America. Trump’s erratic behaviour is combining with other factors to make the systematic risk picture complicated and unpredictable. On the one hand, there have been some excellent results coming out of the S&P500 companies riding the wave of AI.

AI Boom Lifts S&P 500 Earnings 32% as 86% of Companies Beat Estimates | Business | CryptoRank.io

Wall Street investors now expect that the earnings of the S&P500 companies will be roughly 32% higher than they were a year ago as second quarter earnings dramatically exceed analysts’ expectations. 86% of S&P500 companies have now reported earnings above forecast. Alphabet reported second-quarter earnings that included a $98 billion gain, while Amazon recorded $53.4 billion in non-operating pre-tax income, primarily related to its Anthropic investments. Nvidia’s revenue in the second quarter was $96,2bn – more than double the same quarter last year.  

On the negative side, the price of North Sea Brent oil spiked up to nearly $110 per barrel last week, but has now fallen back to just below $100. This decline to $100 comes because of new hopes for peace negotiations such as planned meetings between Gulf and Iranian foreign ministers. These hopes helped ease immediate fears of a total, prolonged blockage of the Strait of Hormuz. At the same time, oil producers in the Persian Gulf shifted shipments to alternative pipeline capacities and non-Middle Eastern regions (like the US, Canada, and Ghana) which increased output to bridge supply gaps. Finally, major international bodies, including the International Energy Agency indicated that there was slowing consumption and a broader economic slowdown, and notably reduced oil demand from major importers like China driven partly by the transition to electric vehicles.

In the middle of all this, on Tuesday and Wednesday this week the US Federal Reserve Bank’s monetary policy committee will be meeting to decide on the future course of interest rates, and they will be focusing on these figures.

https://coinpaper.com/35641/stock-market-today-sp-500-nasdaq-jump-1-as-oil-falls-despite-hot-cpi

The US inflation rate for August 2026 came in at 3,4% for the year to the 31st August 2026. This was the same rate as July and shows broad increases across both goods and services with the price of gasoline being the major contributor. In the month itself, inflation was 0,4% because of a 3,9% increase in the price of gasoline.

Following hotter-than-expected August inflation data, market metrics and prediction venues show a massive shift toward monetary tightening. The CME Fedwatch Tool suggests that the probability of a 25 basis point hike in  interest rates is now between 84% and 87% while Polymarket says there is an 81% probability. A hike in interest rates will add to the misery of consumers in America already facing an average price across the country of $4.30 per gallon of petrol.

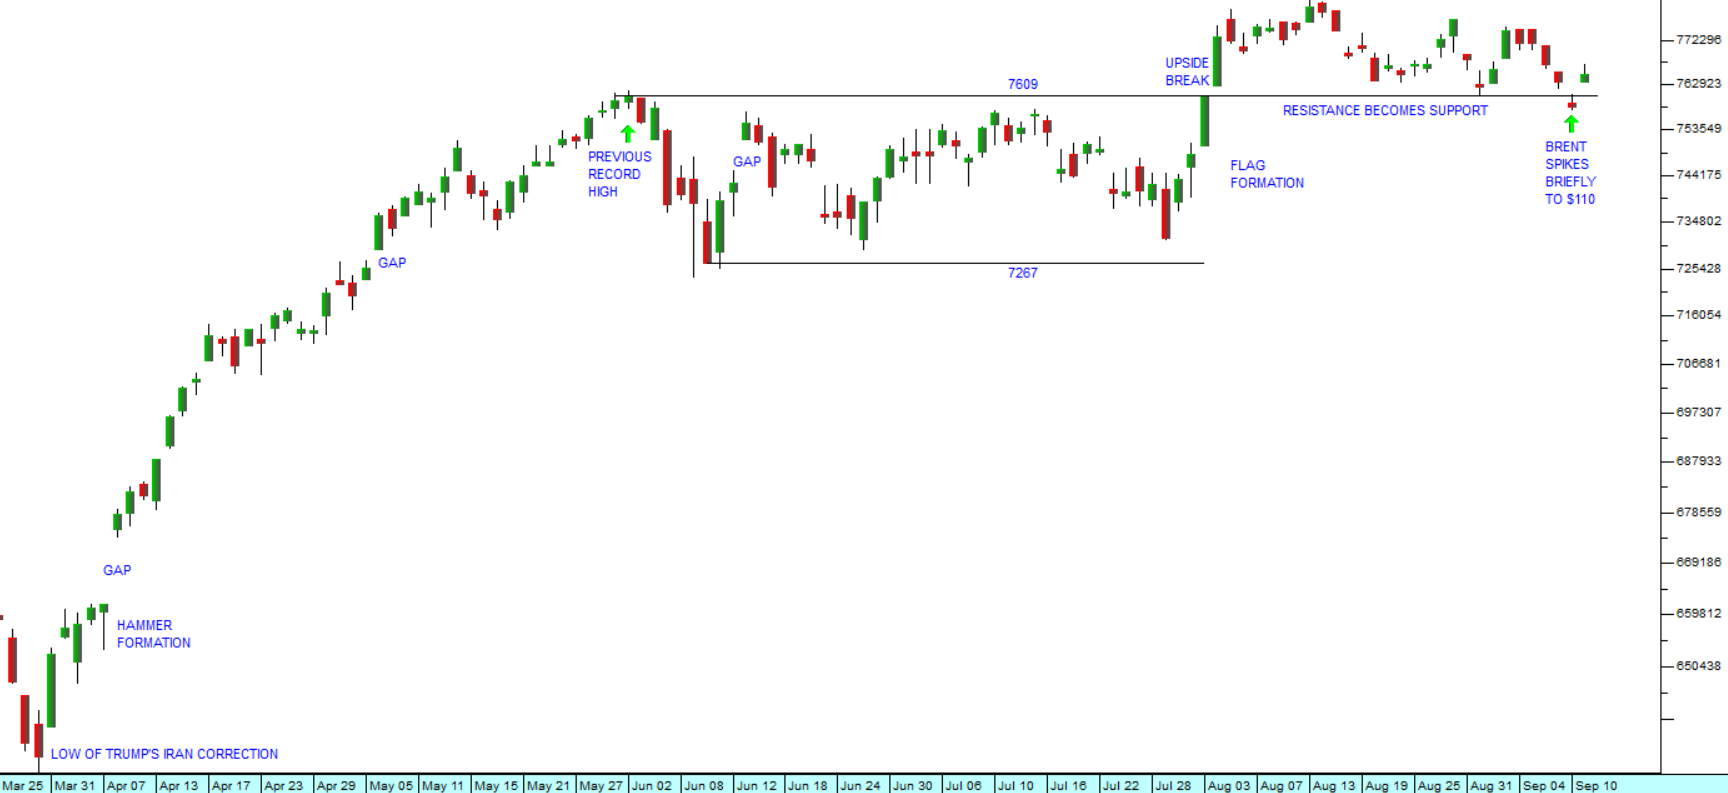
The S&P500 index has been trying to discount all these disparate forces and is basically moving sideways since it broke above the key support/resistance level at 7609. Consider the chart:

S&P500 Index : 25th March 2026 - 11th of September 2026. Chart by ShareFriend Pro.

There can be little doubt about the bullish sentiment which underlies the extended sideways market in the S&P. The news coming from big tech companies appears to be slowly overcoming the bad news coming out of the Middle East. The unexpected spike in the oil price to $110 was short-lived, but it did unnerve the market for a day. That was quickly rectified the next day.

And in the background is the looming mid-term election in America, which is increasingly focusing the Trump camp’s attention, resulting in some radical moves on his part like promising to pay every adult American $5000 if the Republicans win both the House and the Senate. The cost of this is a further $1,23 trillion to be added to the budget deficit already above $40 trillion. He also said that after the elections the petrol price will drop back to $2 per gallon – and anyone who believes that is not following what is happening on the ground.

Trump approval rating hits new low over Labor Day weekend

The Focaldata/Financial Times poll released on September 6, 2026, found that only 32% of Americans now approve of Trump's job performance. Trump's approval rating dropped three points from the previous month, the lowest since the poll series began in May. Critically, his approval among Republicans fell to 72%, a two‑point decline and a new low for that group. The poll was conducted from August 28 to September 2 with 2,178 U.S. adults surveyed. Only 17% of respondents approved of Trump's handling of inflation and the cost of living, while 69% disapproved.

In our view, the Republicans will almost certainly lose the House and the Senate race is now a “toss-up”. If he loses both, we can expect impeachment proceedings to commence promptly.

The S&P500 and markets around the world will ultimately be drawn higher by the AI driven boom in American and elsewhere. We expect new record highs on all indexes in due course.

The Currency  (2026-09-07)

Perhaps the best way to measure the progress of South Africa as a country is to look at our currency – especially against the so-called hard currencies of the Western World. Its strength or weakness gives a very good overall picture of how the country is doing economically, politically and in terms…

Perhaps the best way to measure the progress of South Africa as a country is to look at our currency – especially against the so-called hard currencies of the Western World. Its strength or weakness gives a very good overall picture of how the country is doing economically, politically and in terms of its image with overseas investors.

As an emerging economy, South Africa is not regarded as a poor country, but rather as one which is striving to become first world. For overseas investors this typically means a country and a currency which offers high risk and high potential return. Whereas a 10-year US Treasury Bill can offer the international investor a return of 4,8%, a South African 10-year government bond offers around 8,8% - that is 4% better, if the investor is prepared to take the risk of investing here.

We have a number of advantages over other emerging markets. Perhaps most importantly, we have relatively low inflation. In fact, due to the tireless efforts of Lesetja Kganyago, Governor of the Reserve Bank, our inflation rate is very comparable to many First World countries – and certainly far better than many of the other emerging economies. For example, Turkey’s inflation rate is 31,5%, Argentina is at 33,8% Egypt is at 14,9% and Columbia is at 6%.

We are generally grouped among those less risky emerging economies with lower inflation rates like Brazil (4,6%), India (4,4%), Mexico (3,4%), Indonesia (2,9%), and South Korea (2,8%). These are very comparable to the inflation rates of First World economies like Europe (3,3%), the United Kingdom (2,9%) and America (3,4%).

Approximately $19bn worth of rands are traded in our currency market every day on average. This makes it a highly liquid and very free currency exchange. Overseas investors can quickly take or sell large positions in what is a strong and well-organised market. This has tended to mean that the rand has become a proxy for all emerging economies. When international sentiment is risk-on they pile into our currency and government bonds. When it is risk-off, as it was when Trump began his war with Iran, they sell out quickly.

But overall, for at least the past 17 months the rand has been steadily appreciating against most first world currencies. In our view, this is related to the stabilising impact of the government of national unity (GNU) and the fact that the ANC is no longer in complete control. This together with the various initiatives set in motion by President Ramaphosa have meant that the economic environment has been steadily improving since April 2025.

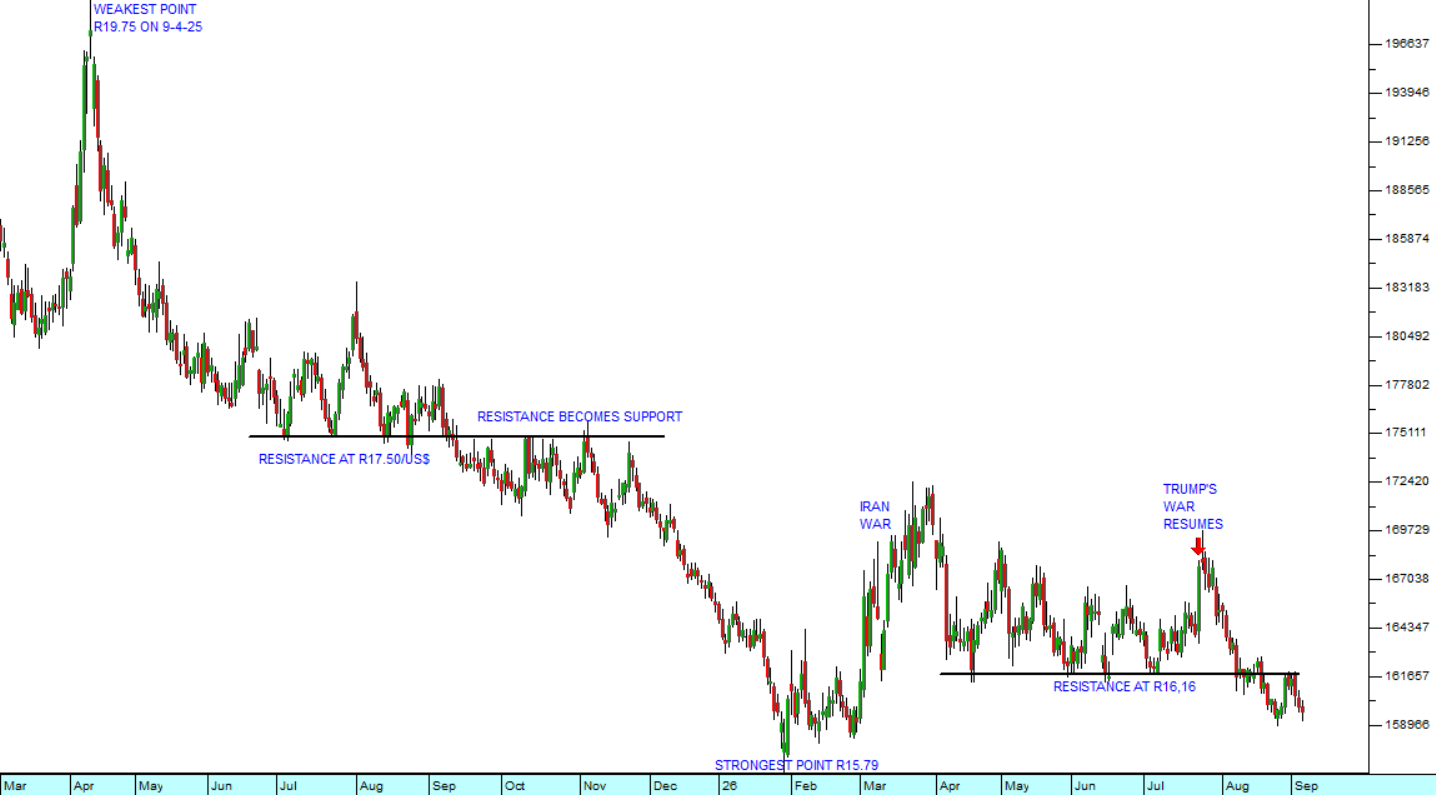
On 10th April 2025 one euro would have cost you R21,90 and today it costs R18,53. On the same day, one British pound would have cost you R25,34 whereas today it costs only R21,56 and of course over the same time period the US dollar has fallen from being worth R19,75 to being worth R15,96. Consider the chart:

South African rand/US dollar : March 2025 - 4th of September 2026. Chart by ShareFriend Pro.

What is significant about this chart is that it clearly shows the steady improvement in international sentiment towards South Africa. The massive, well-informed international investors of the world are betting on our country and putting their money here instead of elsewhere. That is a significant vote of confidence and one which many South Africans caught up in the cut and thrust of daily life here do not appreciate.

In our view, the rand is about to break below its previous cycle low of R15.79 to the US$ made on 29th January 2026. The outcome of the municipal elections on 3rd November 2026 will have a significant impact. If the ANC loses further ground and the DA gains ground (which is what we believe will happen) then you can expect the rand to appreciate further.

A stronger rand is good for everyone in South Africa. It means lower fuel prices, lower inflation, lower interest rates, more stability and a better future for everyone involved in the economy. It is the most telling and reliable indicator of our progress as a nation.

JSE Top 40

105,242.00 (-1.23%)

All Share

113,002.00 (-1.01%)

Financial 15

25,500.00 (-0.62%)

J200
J203
J212
Top Gainers
# Code Name Close (c) % move
1 MTU MANTENGU 21 +23.53%
2 SDO STADIO 1849 +22.86%
3 EUZ EUROMET 489 +22.25%
Top Losers
# Code Name Close (c) % move
1 QFH QUANTUM 650 -20.63%
2 TPC TRNPACO 3905 -15.11%
3 BAC AFBITCOIN 298 -15.10%

Top Movers – Charts

Top Gainer: MTU
Top Loser: QFH